Mortgage Portfolio Risk
18 of 19
High-risk loans in the portfolio that were written by one office, Newark.
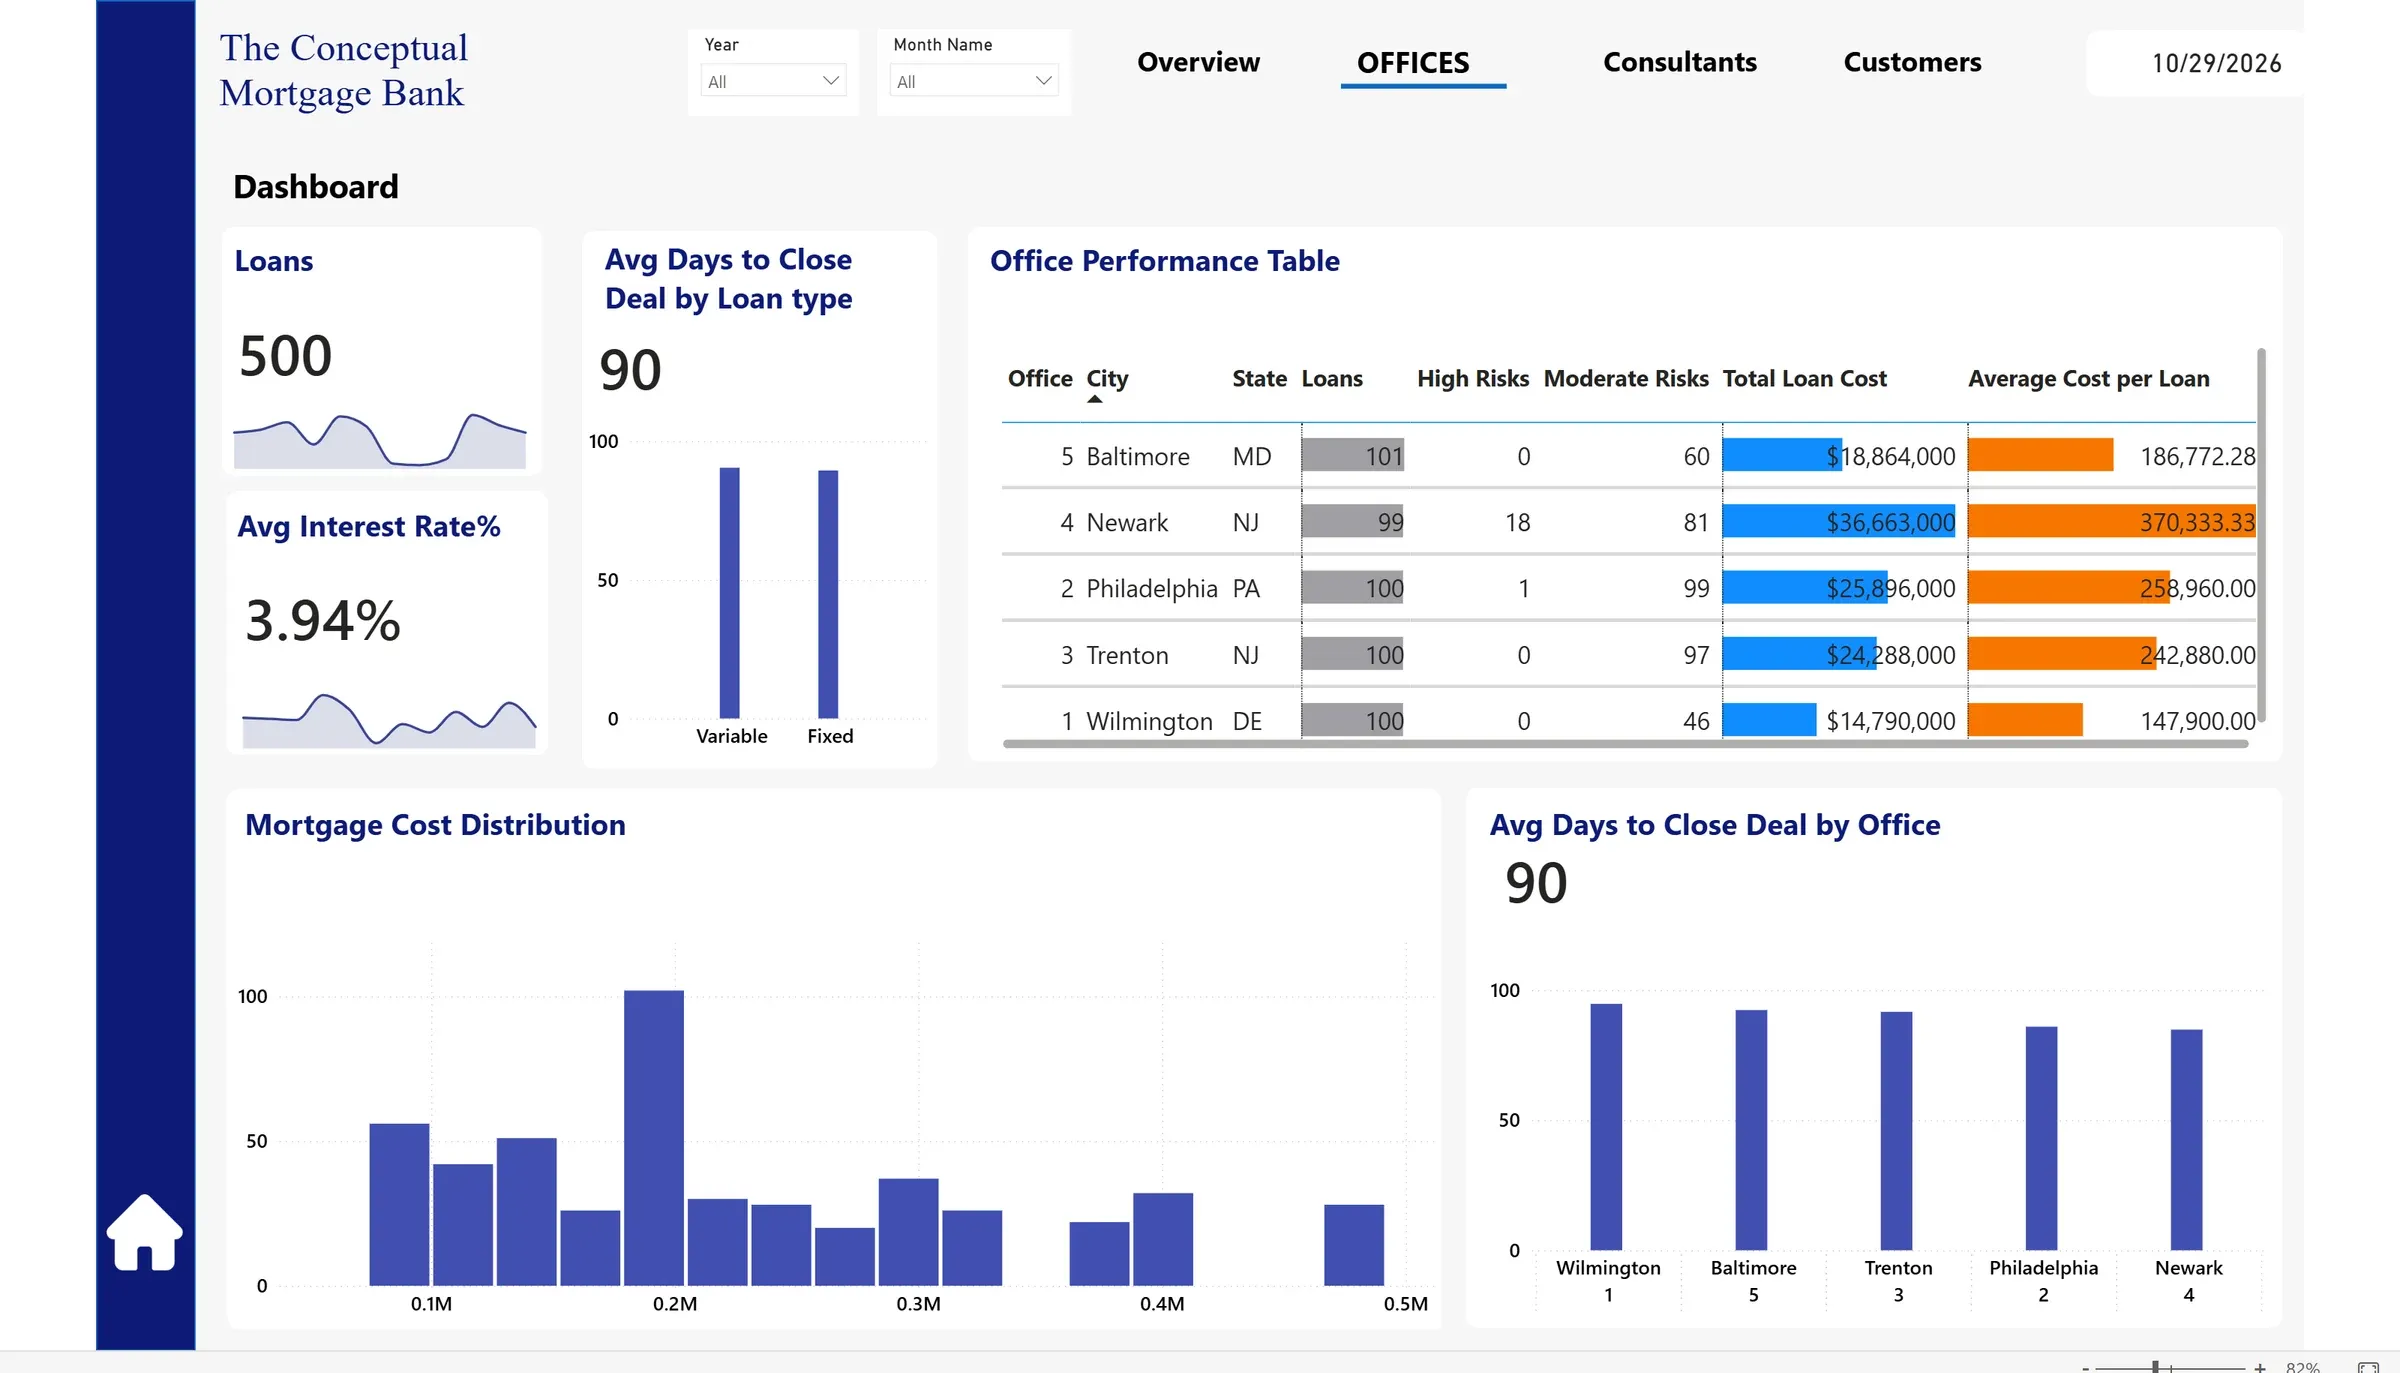
A risk score for every loan in a four-year mortgage portfolio, built in DAX from credit score, loan-to-value and loan-to-income, then used to find where the risk sits and who writes it.
The question
A mortgage bank wanted to know how its loan costs are distributed, whether its risk clusters, how its loan consultants perform, and which borrower characteristics go with high-risk loans, across 2017 to 2020.
The data and the model
The data came in several Excel sheets covering five dimensions, with every transaction feeding one fact table. I cleaned it, modelled it as a star schema, and derived loan-to-value and loan-to-income for each loan. Then I combined them with the credit score into one risk score, each part scaled to 0–10:
Risk Score =
VAR normcreditscore = (([Total Credit Score] - 300) / (850 - 300)) * 10
VAR normLTI = (([Loan-to-income] - 0) / (25 - 0)) * 10
VAR normLTV = (([Loan to Value (LTV)] - 0) / (2.5 - 0)) * 10
VAR finalriskscore = (0.40 * normLTI) + (0.4 * normLTV) + (0.2 * normcreditscore)
RETURN finalriskscore
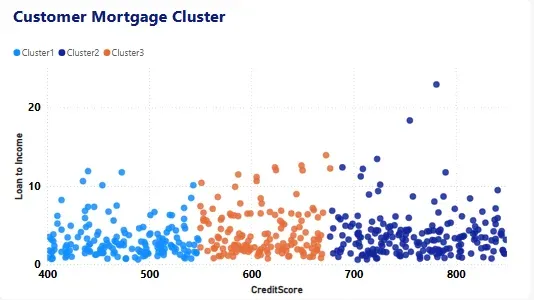
The score sorts every loan into low, medium or high risk, and a cluster analysis groups borrowers by the same factors.
What I found
- Most mortgages sit between $100K and $200K.
- Total loan cost grew 236.44% from 2017 to 2018, because more loans were issued, not larger ones.
- High-risk loans doubled in 2019, yet total loan cost fell only 10%: volume drives cost more than risk.
- Newark wrote 18 of the portfolio’s 19 high-risk loans and has the highest total loan cost. Its borrowers take large loans of $300K to $500K on the strength of high credit scores.
- Wilmington and Baltimore wrote no high-risk loans at all.
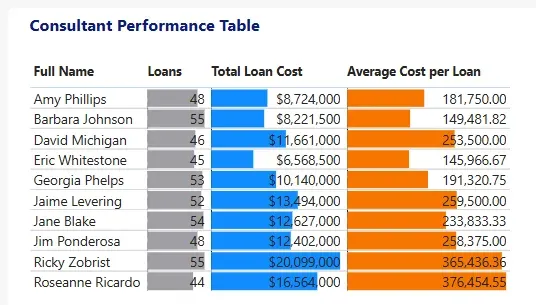
- The top consultant by loan cost, based in Newark, writes high- and medium-risk loans. The consultant in Wilmington writes only low and medium risk and ranks second lowest.
What I recommended
Stricter credit assessment for Newark applicants, a loan-to-income cap for high-risk applicants with good credit scores, interest rates priced by each city’s risk, and coaching that brings the two consultants’ approaches closer together.
The live dashboard
The report as published in Power BI. Use the arrows at its foot to move between pages.